Gold And Silver Are Back In The Buy Zone
A sharp drop on Wall Street last week led to a general “risk off” reaction across financial markets, which pressured the precious metals complex lower.
And even though the US Federal Open Market Committee (FOMC) held rates unchanged, the metals were unable to rally on softer Treasury yields as energy prices rose on increasing tensions in the Persian Gulf.
The daily price charts are now approaching key 52-week support levels, which have historically been attractive for long-term entry points for Gold, Silver, and Platinum.
Physical Gold priced in USD fell to a 12-month low at $3865.00 and finished the week 3.1% lower at $3875.00. The daily Relative Strength Index (RSI) is 29.30, which is a deeply oversold reading.
It’s worth noting that USD Gold rallied 17.5% from November 1st, 2025, to January 1st, 2026.
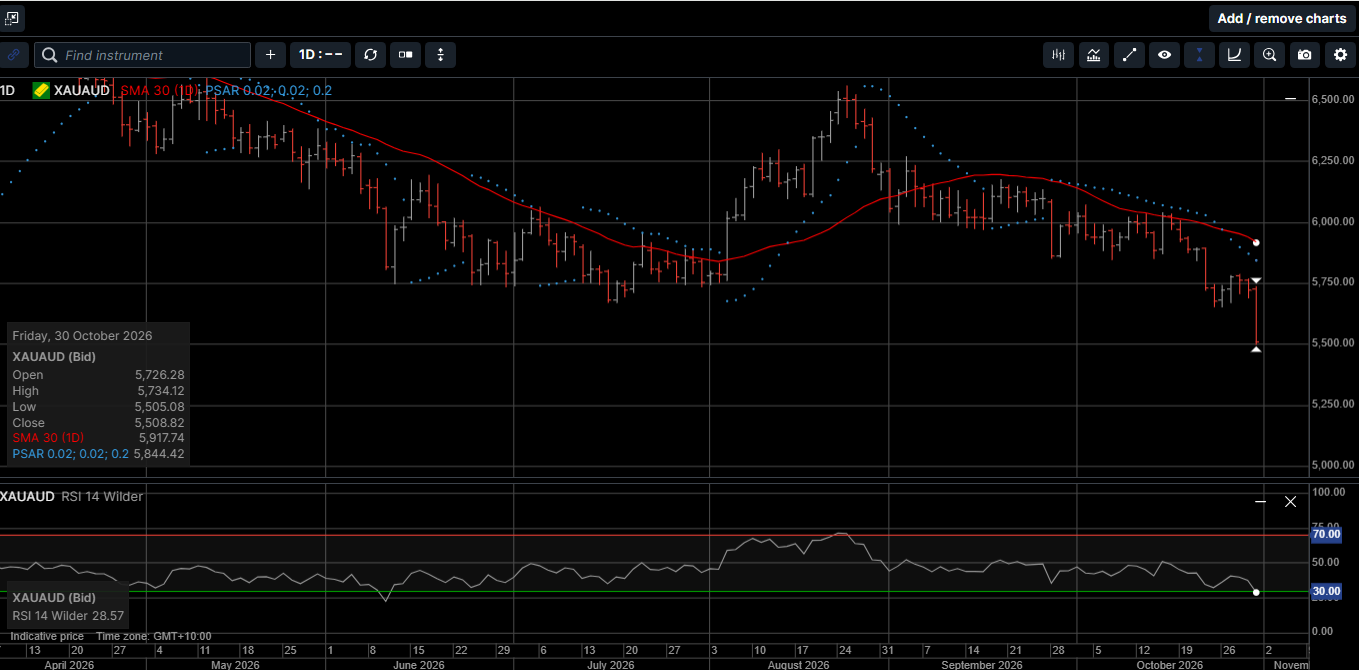
Gold denominated in AUD slipped to a 13-month low at $5505.00 and closed out the week 2.9% lower at $5508.00. The daily RSI is also flashing an oversold reading at 28.50.
Similar to USD Gold, AUD Gold finished last year with a 23.2% gain from November 1st to January 1st.
Physical Silver priced in USD hit a 13-month low at $47.25 before drifting higher to finish the week 8.9% lower at $49.10. The daily RSI is showing a three-year low at 23.75, which is deeply oversold.
USD Silver rallied over 77% between November 1st, 2025, and the end of the year.
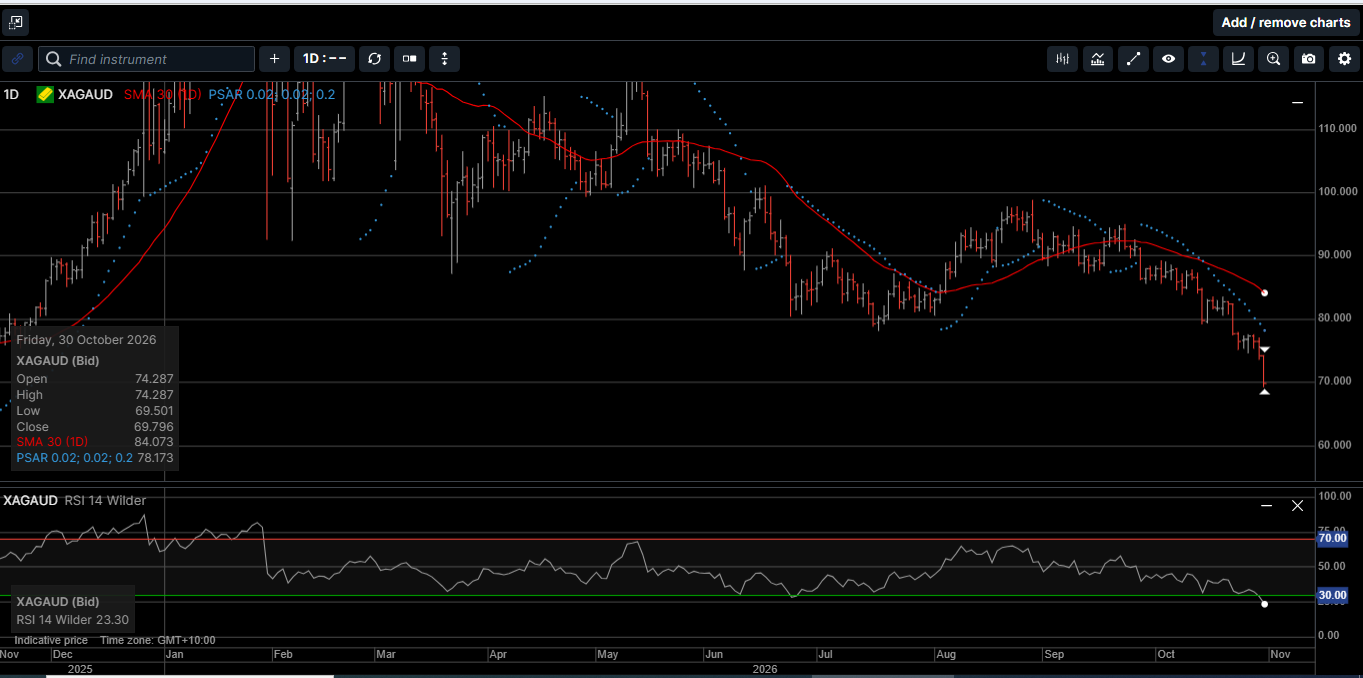
Silver denominated in AUD hit a 12-month low at $69.55 and finished the week with an 8.8% loss at $69.80. The daily RSI is deeply oversold at 23.30.
AUD Silver returned a whopping 79.30% from November 1st to the end of the year.
The Gold versus Silver ratio rose 6.45% in favor of Gold and closed at a 10-month high at 78.80, which means it takes 78.80 ounces of Silver to equal the price of one ounce of Gold.
The daily RSI on the ratio hit an 18-month high at 77.40, which is an overbought reading. As such, we would expect Silver to outperform Gold over the medium-term.
Physical Platinum fell to a 13-month low at $1422.00 and posted a weekly loss of 7.7% to close at $1432.00. The daily RSI is 24.80, which is its lowest level since June 15th, 2021.
Platinum rallied an eye-watering 80.5% between November 1st to the end of last year.
As mentioned above, last Wednesday the US FOMC kept its FED Funds policy rate unchanged in the range of 3.75% to 4.0%, as widely expected.
What was not expected were the two hawkish dissents – by FED Governor Lisa Cook and Cleveland Fed President Beth Hammack – who preferred a rate hike, despite the election this week.
The 10-year Treasury yield instantly jumped by 4 basis points to 5.04% after the announcement but finished the week at a two-month low at 4.90%.
FED Chief Kevin Warsh has been adamant about not providing forward guidance and is carefully staying away from hints about future FED moves.
However, the other 11 voting members of the FOMC are not necessarily on the same bandwagon, and some are decidedly and vocally off that bandwagon.
So, is it reasonable to think that seeing longer-term bond yields slip lower after the FOMC announcement is the market version of forward guidance, and is the FED on hold until at least Q1 of 2027? We believe that this is the case.
As illustrated on Chart 1, as interest rates climb higher, the outstanding losses on the FED’s balance sheet increase at a faster pace since they are leveraged.
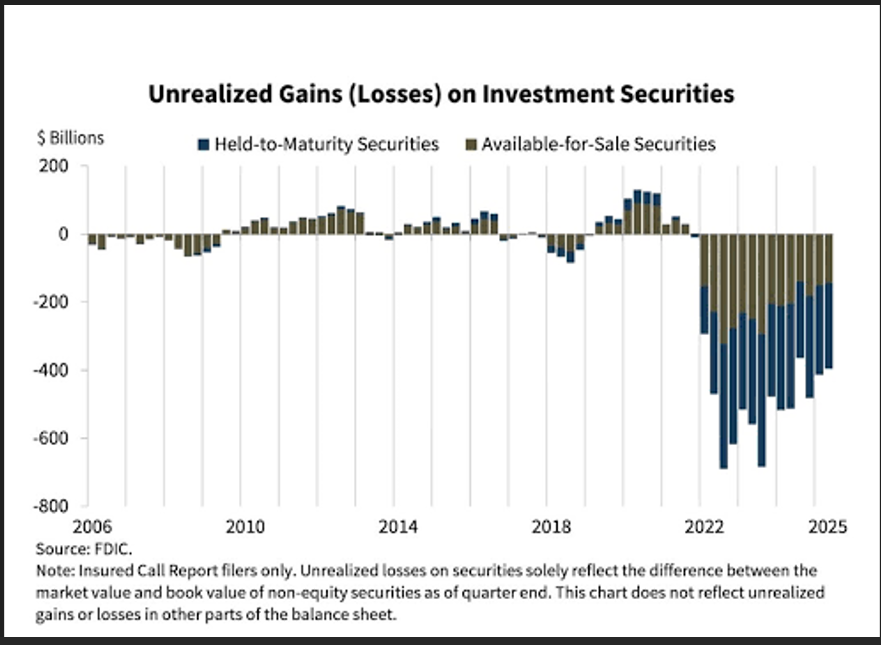
Chart 1 only includes open losses as of the end of 2025. Factoring in the September rate hike, these open losses are probably closer to $700 billion and growing.
During the post FOMC press conference, Mr. Warsh linked FED rate policy to the US Administration’s fiscal policy.
As shown on Chart 2, there is a direct mathematical correlation between the FED Funds rate and the rising cost of paying the interest on the US national debt.
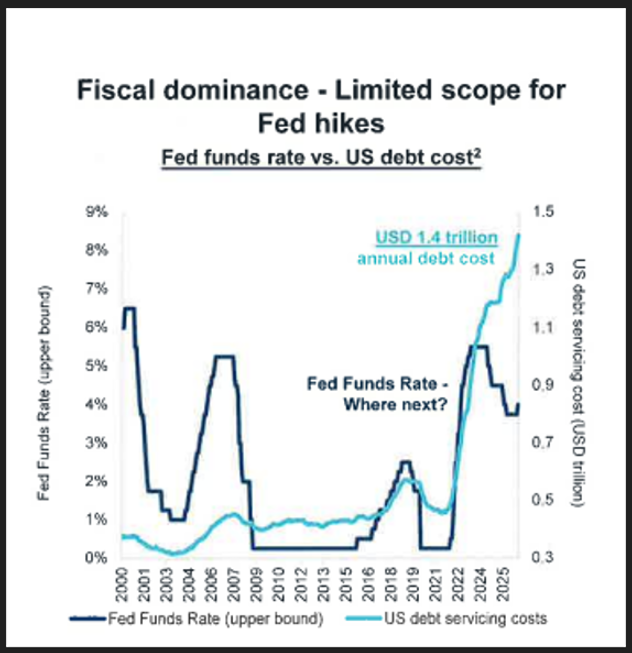
If Mr. Warsh is serious about formulating FED policy to assist the administration in slowing down the rise in the debt servicing burden; then the FED would be talking about lowering the FED Funds target, not raising the target.
We believe the drop in longer-dated bond yields last week is evidence that both the FED and the US Treasury department would rather see the recent energy-based inflation run hotter, as opposed to creating an interest rate driven economic recession.
As this narrative gains traction, and the USD weakens versus the G-20 crosses, it’s reasonable to expect Gold, Silver and Platinum to extend their long-term trends higher.
Further, as shown on Chart 3, since 2017, Gold has fundamentally been increasing its role as a global reserve asset.
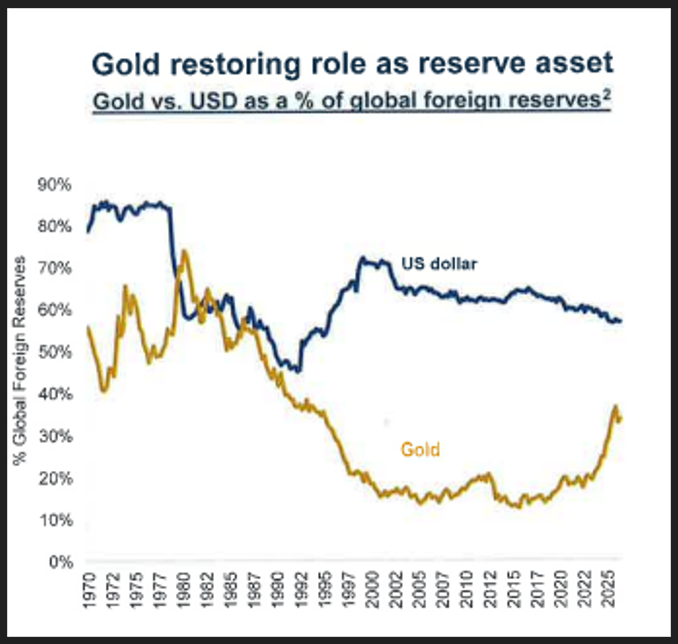
From a technical perspective, the recent pullback in the precious metals complex looks to be running out of downside momentum, which suggests a sharp, mean reversion rally could happen over the near term.
The multi-year supply/demand deficits in Gold, Silver, and Platinum are still intact and are growing.
Central banks and institutions are aggressively buying hard assets to diversify risk and as a traditional store of value
As such, now is the time to consider adding to your hard asset holdings and making physical Gold, Silver and Platinum the cornerstone assets in your long-term wealth creation strategy.
This publication has been prepared for the GBA Group Companies. It is for education purposes only and should not be considered either general of personal advice. It does not consider any particular person’s investment objectives, financial situation, or needs. Accordingly, no recommendation (expressed or implied) or other information contained in this report should be acted upon without the appropriateness of that information having regard to those factors. You should assess whether or not the information contained herein is appropriate to your individual financial circumstances and goals before making an investment decision or seek the help the of a licensed financial adviser. Performance is historical; performance may vary; past performance is not necessarily indicative of future performance. Any prices, quotes or statistics included have been obtained from sources deemed to be reliable, but we do not guarantee their accuracy or completeness.